
Clear to close in 14 days
ICE tracks closings nationwide and puts the typical file at about 38 to 42 days. That 14-day number is the average for our files. We underwrite and fund here, so the file does not sit in some national underwriting hub.
NMLS 2647764
Egan Financial Group LLC is a licensed Independent Mortgage Banker (IMB). We take the application, underwrite the file, and fund the loan in our own name. Stadium ads, outside investors, and extra companies in the middle of a loan raise the rate. We cut that cost so you are not paying a higher rate for it.

Why I built this shop
Who is Bill Egan?
My name is Bill Egan, NMLS 7342. I built Egan Financial Group LLC (NMLS 2647764) into a new class of IMB called a micro mortgage banker. That means I take your application, underwrite the file, and fund your loan in my company’s name.
I left a large retail lender when overhead made it hard to offer my clients a competitive rate. Becoming a broker again was not the answer — brokers have to rely on a middleman to fund the loan. The only way to beat the big lenders and the brokers was to become a full-service Independent Mortgage Banker: I take the application, approve the file, and fund the loan.
Egan Financial Group LLC was built to deliver the lending power of a major bank without the corporate bloat that drives up rates. Because I control the process from application to closing, my borrowers get better pricing, faster turn times, and direct accountability — from me.
ICE tracks closings nationwide and puts the typical file at about 38 to 42 days. That 14-day number is the average for our files. We underwrite and fund here, so the file does not sit in some national underwriting hub.
Egan Financial Group LLC is the lender. There is no broker markup and no corporate overhead built into the rate.
The file is underwritten here, to investor guidelines — not dropped into a national queue. If something is missing, you hear from the person who needs it.
Most mortgage closings run 45 to 90 minutes. Ours average 35 to 60 minutes because we send the money to the title company in advance — no “waiting on the wire.”
Refinance
When you close a purchase loan with Egan Financial Group LLC and you come back to refinance later, you get a $2,000 lender credit to offset your closing costs.
Loans
I originate, underwrite, and fund home purchases. Start with how much house and cash you need, then a real pre-approval — not a letter based on what you typed in a box.
Learn moreI refinance as the lender, not a broker sending your file to someone else. Rate-and-term, cash-out, and VA streamline. I run break-even in months before anyone orders a payoff.
Learn moreI originate, underwrite, and fund VA purchase, cash-out, and IRRRL loans for eligible Veterans. Funding fee, Certificate of Eligibility, and residual income are a real loan file, not a brochure.
Learn moreMortgage FAQs
The problem that brought you here. Where it goes wrong. What we do about it. How to get ready. Written by Bill Egan, NMLS 7342.
Most sellers in our market expect one to three percent of the purchase price as earnest money. That is the deposit you put down to show you are serious about buying the house. The exact amount is negotiated in the purchase contract. We help you decide a number that is strong enough for the seller without tying up more of your cash than you need.
Read the full answerA final walk-through is your last chance to check the house before you sign the papers and take ownership. You walk through with your agent to make sure the seller completed any agreed repairs, left the home as promised, and removed their belongings. Problems found then can still be fixed or credited before the keys change hands. We stay available on your file so a last-minute issue does not delay the funding.
Read the full answerA financing contingency is a clause in your purchase contract that lets you cancel and get your earnest money back if you cannot get the mortgage you need by the deadline. Earnest money is the deposit you put down to show the seller you are serious. Without the clause, a denied loan can mean you lose that deposit. We track the deadline on your file so you know when the protection ends.
Read the full answerPrivate mortgage insurance, or PMI, is a monthly cost added when you put less than 20 percent down on a conventional loan. It protects the lender if you stop paying. You do not pay it forever. The law lets you request cancellation once you reach 20 percent equity based on the original value, and it must drop off automatically at 22 percent. We show the PMI amount on your Loan Estimate so you know the full payment before you write an offer.
Read the full answer
DIY calculator
Estimates of local taxes and insurance, by county. Conventional, FHA, VA, and jumbo. The current average rate follows the HousingWire print. Not a quote.
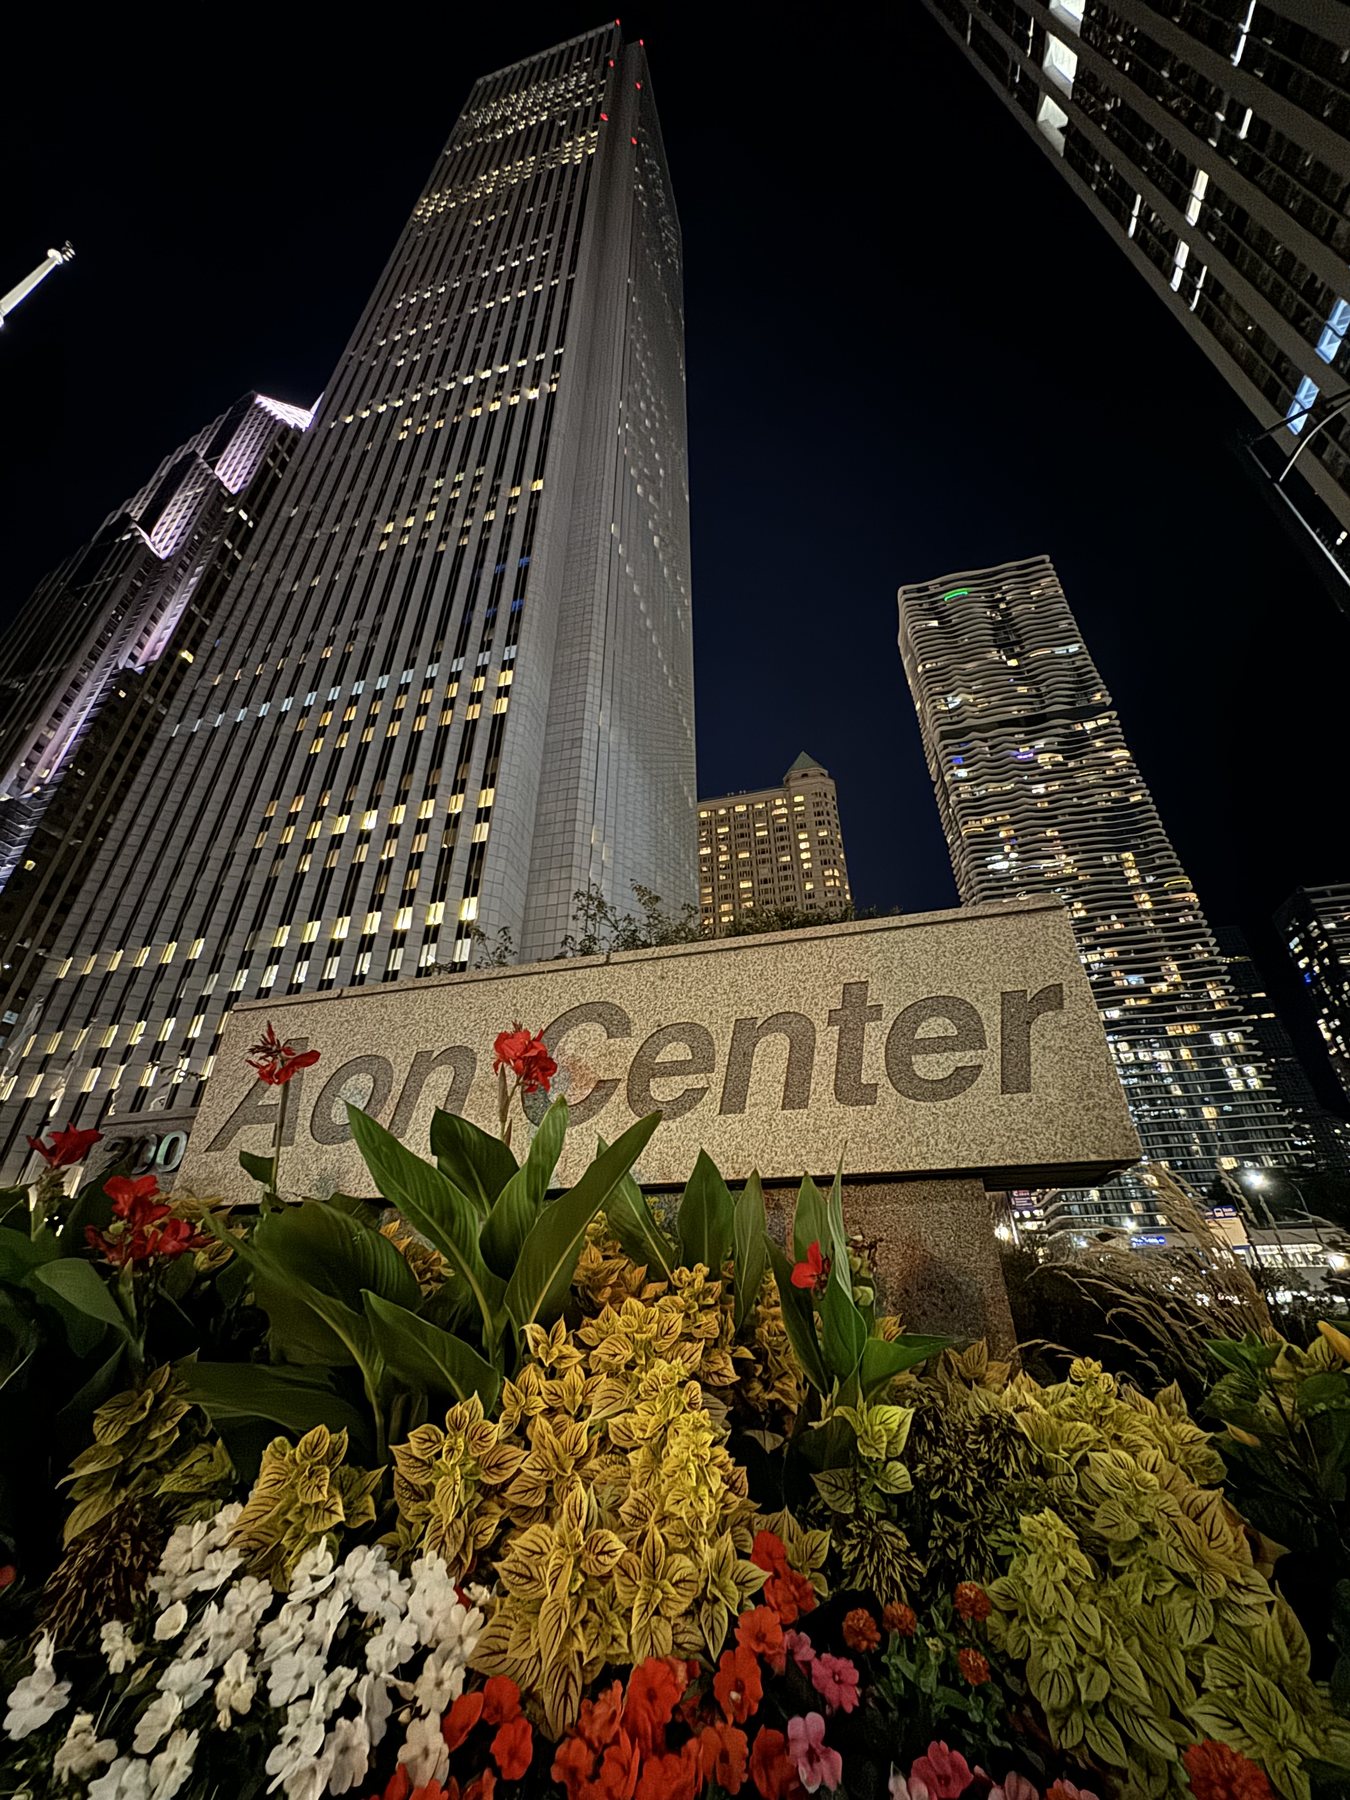
Headquarters
200 East Randolph Street
Suite 5100
Chicago, IL 60601
312-919-0859
By appointment, Monday–Saturday