
Clear to close in 14 days
ICE tracks closings nationwide and puts the typical file at about 38 to 42 days. That 14-day number is the average for our files. We underwrite and fund here, so the file does not sit in some national underwriting hub.
NMLS 2591169 · Company 2647764
Buying your first house can feel complicated. The loan should not. I’m Rachael Smith, co-founder of Egan Financial Group LLC. We are a licensed Independent Mortgage Banker (IMB). We take the application, underwrite the file, and fund the loan in our own name.
Why I helped build this shop
Who is Rachael Smith?
I’m Rachael Smith, NMLS 2591169, co-founder of Egan Financial Group LLC (NMLS 2647764). Buying your first house can feel complicated. The mortgage should not. I take your application and stay on the file. The company underwrites and funds the loan in our own name.
What does a micro mortgage banker mean for you?
It means you are not handed off after you apply. We have the power of a larger lender without stadium ads and a floor of managers that raise the rate. I stay involved from the first call through closing. You have someone who knows your loan and will pick up the phone.
Why does underwriting experience matter?
I started as a processor — the person who gathers pay stubs, bank statements, and tax returns. Then I was an underwriter at a large lender. An underwriter is the person who decides if the loan can close. I have deep underwriter experience. I catch a problem while we can still fix it, not three days before you get the keys.
ICE tracks closings nationwide and puts the typical file at about 38 to 42 days. That 14-day number is the average for our files. We underwrite and fund here, so the file does not sit in some national underwriting hub.
Egan Financial Group LLC is the lender. There is no broker markup and no corporate overhead built into the rate.
The file is underwritten here, to investor guidelines — not dropped into a national queue. If something is missing, you hear from the person who needs it.
Most mortgage closings run 45 to 90 minutes. Ours average 35 to 60 minutes because we send the money to the title company in advance — no “waiting on the wire.”
Refinance
When you close a purchase loan with Egan Financial Group LLC and you come back to refinance later, you get a $2,000 lender credit to offset your closing costs.
Loans
Egan Financial Group LLC originates, underwrites, and funds home purchases. Start with how much house and cash you need, then a real pre-approval — not a letter based on what you typed in a box.
Learn moreWe refinance as the lender, not a broker sending your file to someone else. Rate-and-term, cash-out, and VA streamline. We run break-even in months before anyone orders a payoff.
Learn moreWe originate, underwrite, and fund VA purchase, cash-out, and IRRRL loans for eligible Veterans. Funding fee, Certificate of Eligibility, and residual income are a real loan file, not a brochure.
Learn moreMortgage FAQs
The problem that brought you here. Where it goes wrong. What we do about it. How to get ready. Reviewed by Rachael Smith, NMLS 2591169.
Yes. A parent can give you the down payment on most purchase loans, and so can other close family. A spouse, a brother or sister, a grandparent, and other relatives the program allows can give it too. It has to be a true gift, not a loan you pay back. The file needs a short gift letter, proof the money left their account, and proof it landed in yours or at the title company. A screenshot of a Venmo transfer is usually not enough.
Read the full answerAn attached condo often prices higher than a house because Fannie Mae and Freddie Mac add a fee for that property type. The fee is a percentage of the loan amount, and the lender usually builds it into the rate. On Fannie Mae’s price sheet the big fee is three-quarters of a point when you put down less than 25 percent. At 25 percent down it drops to one-eighth of a point. It is not a sign that your file is worse.
Read the full answerNo. Twenty percent down is a choice, not a rule. Many buyers use about 3 percent on a conventional loan, 3.5 percent on an FHA loan, or nothing down on a VA loan if they qualify. A smaller down payment usually adds mortgage insurance, and you still need cash for closing costs. The number that matters is the full payment you can live with, with money left after you close.
Read the full answerNo. A news headline that the average 30-year mortgage is over 7 percent is a national weekly average. It is not your rate. Your rate depends on your credit, your down payment, the loan type, and the day you lock. Ask for your payment at today's pricing before you decide the house is out of reach.
Read the full answer
DIY calculator
Estimates of local taxes and insurance, by county. Conventional, FHA, VA, and jumbo. The current average rate follows the HousingWire print. Not a quote.
Headquarters
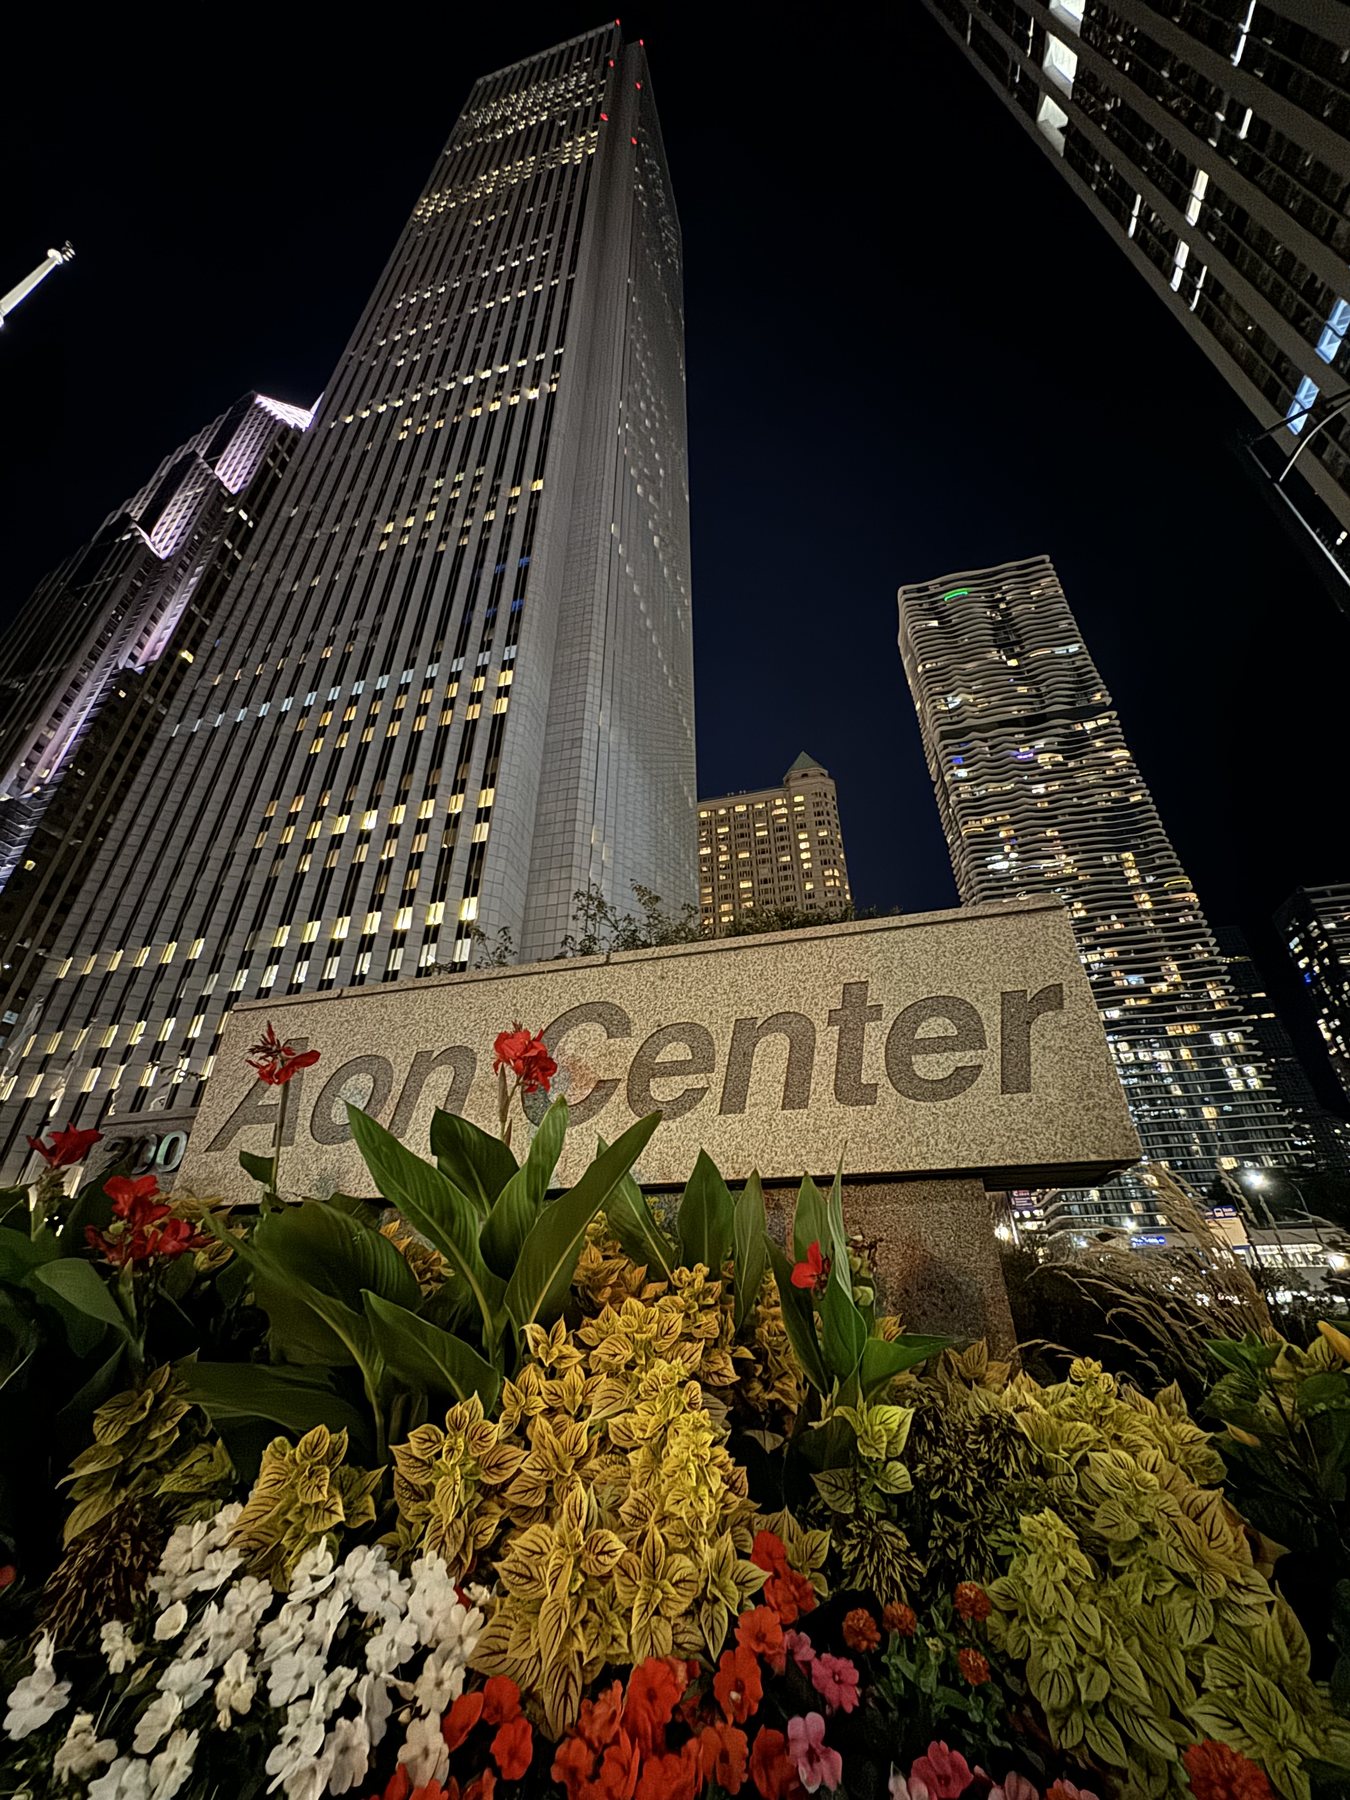
200 East Randolph Street
Suite 5100
Chicago, IL 60601
847-254-6472
By appointment, Monday–Saturday